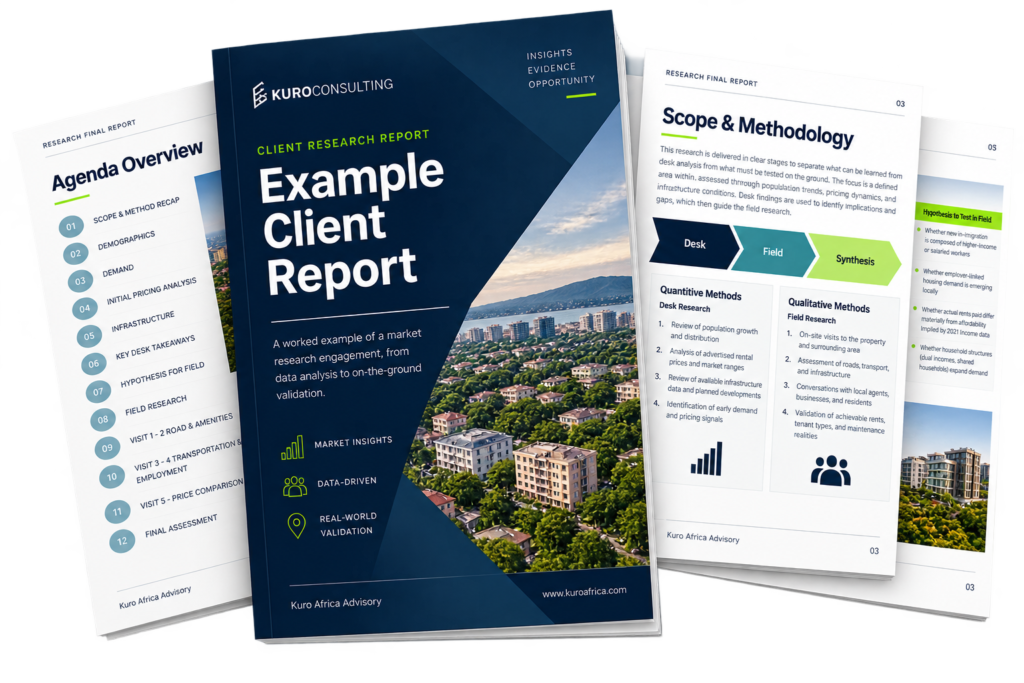
Kuro Africa · Market validation · RentalSample report · Abridged
KUROAFRICASample report
Market validation · Rental asset
A five-unit rental on a growth corridor: who will rent it, and at what price?
A desk-and-field validation for a private owner holding a mostly two-bedroom, five-unit block in a fast-growing district east of Accra. This abridged sample shows how we work and what the client received — not the findings they paid for.
Select a tier to highlight every claim that carries it
Prepared for
A private owner, anonymised at the client’s request
Prepared by
KuroAfrica — independent of developer, agent and landlord
Full report
32 slides · 12 sections · 5 field days · 11 hypotheses tested
This sample is abridged. Client identity, the district and site, named employers, roads and schools, rent bands, the target tenant segment and the recommended pricing are withheld. Where a finding is withheld, the sample says so.
The question was never whether the district is growing
The district is one of the fastest-growing around Accra, and a wave of road, rail, energy and industrial projects is heading its way. That was never in doubt. The client asked something narrower and harder: who will actually rent five mostly two-bedroom units here, what can they realistically pay today — and does the infrastructure pipeline change that answer, or only the one in five years’ time?
Asset
Five-unit rental block, predominantly two-bedroom
Geography
Peri-urban growth district east of Accra, anonymised
Decisions
Rent level, tenant targeting, timing against infrastructure delivery
Structure
Desk research · 11 hypotheses for the field · five field days · synthesis
Verdict instrument
KuroScore — seven criteria, each scored out of 5
02How we worked
Desk first, then the ground, then one standard of evidence
Desk analysis tells you what the data implies. It cannot tell you what a tenant will pay, how long the commute really takes at 9:30 on a Tuesday, or whether a listing is actually let. So every desk finding ended as a hypothesis, and the field days were built to test them.
Three stages
Desk — population, age and employment structure; affordability modelled at a test rent; asking-rent analysis from our listings dataset; a 20-project infrastructure pipeline
Hypotheses — 11, across demographics, pricing and infrastructure, each written to be confirmed or rejected on the ground
Field — timed drives, employer-zone interviews, rail service checks, offline listings and agent tours
Synthesis — hypothesis results, an implications matrix and a KuroScore
Fieldwork
Days 1–2 — Roads, commute timing, amenities, schools2
Days 3–4 — Rail service and the main employment zone2
Day 5 — Offline listings, agents and a three-area price comparison1
Conversations with entry-level workers, supervisors, agents and landlords, plus tours of listings with little or no online presence.
Every claim carries its evidence tier
This is the single most important thing we sell. Every claim of fact in a KuroAfrica report is tagged, and a tier is never upgraded to make a finding land harder.
TierMeansHow it appears in this engagement
Data, independent press, or confirmed public record.
Census population, age and employment structure; the listings dataset; a timed outbound drive.
One source, no independent confirmation.
A supervisor’s stated maximum rent budget and his five-hour daily commute.
A reading supported by the data, not directly measured.
An affordability ceiling modelled from census income data; inbound peak commutes likely exceeding two hours.
Stated plainly as unknown.
Whether announced industrial projects deliver their job numbers on schedule.
03Selected findings
Growth is real. Rent-paying capacity is the constraint.
The growth story
2021 census and district projections
Population projected to grow by roughly 70% by 2040 — about 3.7% a year
Over half the population is aged 15–44, and nearly 80% live in urban localities
Around 54% of adults are employed, the majority in private informal work
A growth market, not yet a rent market
At a test rent of GHS 3,000 a month, only about 6–7% of employed workers could pay without stress. Population growth does not become rental demand on its own — income and employment structure decide who can actually pay.
Modelled from census income data
What the field added
Worker and supervisor interviews
Entry-level workers in the nearby employment zone commonly share accommodation — some contributing around GHS 100 a person a month, including in warehouse-style arrangements. One supervisor actively looking for a closer home currently commutes close to five hours a day. Demand exists; it is shared, cost-split and price-capped.
Field day 5 · “To let” signage and agent calls
A significant share of rental activity never appears online, and agent presence was close to non-existent. A toured upper-band block, priced in line with the market for its size but poorly maintained and missing basic utilities, showed no sign of genuine tenants — the occupants appeared to be caretakers.
Withheld
Rent bands across the three catchment areas, the fastest-occupancy and stretch price points, the area price hierarchy, named employers, and the tenant segment the client should target first.
We mapped 20 projects: 40% road and rail, 30% energy and utilities, 20% industrial, 10% leisure and tourism. A new commuter rail service is reliable and well used — but no one we spoke to cited it as a reason to live in the district.
Road & rail 40%
Energy & utilities 30%
Industrial 20%
Leisure & tourism 10%
Demand will precede price rises
Real pricing power arrives once roads and utilities are visibly complete, not when they are announced. Until then the game is occupancy, positioning and tenant quality — and landlords who wait for infrastructure to “prove itself” enter after rents have moved.
04Hypotheses tested
Eleven hypotheses, written at the desk and settled on the ground
Each hypothesis is stated before fieldwork so it can fail. The full report gives the result, the field evidence and the implication for every one. Five are shown here, without the numbers.
ThemeHypothesisResult
DemographicsMost real renters are tied to nearby employment nodes, not drawn to the district itself.Confirmed
DemographicsCorporate-linked renters exist, but only for a reliable, managed offer.Partially confirmed
PricingThe market has a hard affordability ceiling; above it, occupancy drops sharply.Confirmed
PricingAsking rents are overstated; real deals close after negotiation.Confirmed
InfrastructureThe new rail station is not yet a primary driver of rental demand.Confirmed
06–11Six further hypotheses across demographics, pricing and infrastructureWithheld
Withheld
The remaining six hypotheses, the evidence behind each result, and the implications matrix that turns them into pricing and tenant decisions.
A market validation closes with a KuroScore: seven criteria, each scored out of 5 with a written rationale, and a plain-words reading of what the overall score means for this asset. A weak criterion is never rounded up.
A
Connectivity & accessibility
Road access, rail, and what the commute is really like at peak.
— / 5
B
Employment & demand factors
Who works nearby, and whether they can rent.
— / 5
C
Residential market depth
How much of the market can absorb this stock.
— / 5
D
Pricing power & affordability
Headroom above the dominant rent band.
— / 5
E
Infrastructure trajectory
Momentum of delivery, not announcements.
— / 5
F
Liveability & amenities
What daily life needs, and how far away it is.
— / 5
G
Execution & operating risk
How much the outcome depends on the owner’s own hands.
— / 5
Withheld
The scores, the overall KuroScore and its rationale, the recommended rent levels and the tenant-acquisition route.
This is not a passive-listing market. In a transitioning area, renters pay for certainty — reliable water, backup power, a predictable maintenance response. With little formal property management and most activity running through informal networks, results depend on active, hands-on tenant targeting rather than a price on a portal.
06The full report
What the client received
32 slides across 12 sections, from desk analysis through five field days to a final KuroScore.
SectionContents
01Scope and method recap — what the desk can tell you, and what only the field can
02Demographics: population growth, age and urban structure
03Demand: employment structure and affordability modelled at a test rent
04Initial pricing analysis: asking-rent bands, bedroom mix and example listings
05Infrastructure: the 20-project pipeline by type and delivery confidence
06Key desk takeaways
07Hypotheses for the field — 11, across demographics, pricing and infrastructure
08Field research overview
09Field days 1–2: timed commute, local roads, amenities and schools
10Field days 3–4: rail timetable and reliability, employment-zone interviews
11Field day 5: offline listings, agent checks and a three-area price comparison
12Final assessment: hypothesis results, implications matrix and KuroScore
Evidence before pricing
Holding a rental asset in Ghana?
A market validation tells you who will actually rent your units and what they can pay — before you set a price, furnish or list.
If you already have a number and want it justified, this is not the right engagement.
The call
45 minutes on the property, the stage you are at and any deadline. We scope the question before anything is priced.
What follows
A proposal setting out the desk work, the hypotheses and the field days your answer will rest on.